We live in the most interesting time ever for financial markets.
Today is a case in point; if you don’t find today’s blog fascinating, I will refund your money.
I. Interesting Thing #1: Inflation Comes In Very Hot, But Rates Fell!
Consumer Price Inflation (CPI) came in much hotter than expected yesterday, and rates shot up, as expected.
BUT – rates then fell throughout the day. Then today, the Producer Price Index (PPI) came in blazing hot – and I thought “oh no…, rates are going to scream higher…”
But rates fell despite blazing-hot inflation. Why?
1. The main reason: “Flight to Safety” outweighed inflation concerns.
Concerns about the AI bubble popping sent investors out of stocks and into the safety of bonds, pushing rates down.
2. Core vs. Overall Inflation: “Core” inflation excludes food and energy prices (which tend to be more volatile), and it is much cooler than overall inflation – giving investors some solace.
3. Supply Shock vs. Monetary Inflation: Investors care more about inflation from too much money in circulation than about higher prices from “supply shocks” (like we saw with COVID and the Iran War) – and we’re seeing more of the latter right now.
4. The Fed Talked Down The Likelihood Of A Hike: Fed comments can move rates, as we’ve seen time and again.
But again – the big takeaway is that nobody expected rates to fall in the face of inflation this hot! And – even when everyone expects rates to rise…they can fall.
II. Interesting Thing #2: You Need A Mortgage Credit Crisis And An Inventory Build To Create A Housing Bust!
The “crash bros” are gleefully predicting a housing crash because rates are so high and sales are so slow, and Logan Mohtashami keeps swatting them down like flies.
We need to see these two things before we see a major correction in home prices:
- Excess credit to fuel a bubble – like we saw prior to 2008. Lending standards – with 100% financing and no verifications – were nonexistent. Since 2008, we’ve had very strict mortgage lending standards – so there is NO mortgage credit crisis brewing.
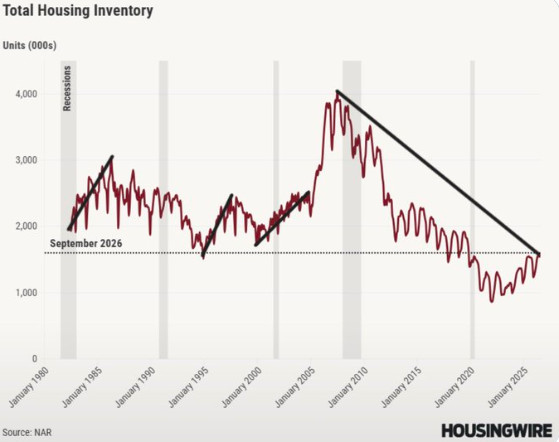
- A flood of inventory – and we’re barely at the trickle stage. This is what the crash bros really get wrong. From a historical perspective, inventory not only isn’t surging, but isn’t even close to historical norms. Mohtashami shared the chart below to drive home his point.
III. Rates Don’t Fall In Election Years. Dispelling The Myth!
Mr. Trump wanted interest rates to fall more than almost anything else this year prior to the midterms – and yet they rose almost 1% since early September despite ALL of Mr. Trump’s efforts to push them down.
My point is this: Prior to every presidential election, everyone repeats the old wives’ tale that “rates fall in election years” – as if politicians have the power to push them down. They don’t.
Mr. Trump will no doubt take credit for today’s rate drop, but he’ll take credit for a sunrise: “I have instructed my staff to make sure the sun comes up tomorrow… Thank you for your attention to this matter.”
Over the last 10 presidential elections, rates fell in six and rose in four. But most of the movements were so small that rates were effectively flat (negligible movement).
So, it’s always about a 50/50 chance whether rates will fall – and it is always the bond market that has the final say.