Every few weeks, I rewatch the movie Apocalypto – a movie that depicts Mayan warriors brutally capturing other Mayans – who then get their hearts ripped out and their heads cut off by Mayan priests in ritualistic sacrifices at the top of a pyramid in front of a bloodthirsty crowd roaring its approval.
I rewatch the movie so often to remind myself that things could be worse when I wake up and see the 10-Year Treasury hit 4.7%. Although I suspect there are a lot of mortgage loan officers who might prefer getting sacrificed right now…
There are comments on X about the 10-Year Treasury not seeing yields this high since 2007. But that is not true. They were higher in October of 2023, when we saw the yield clip 5.0% – and we all thought Armageddon was here.
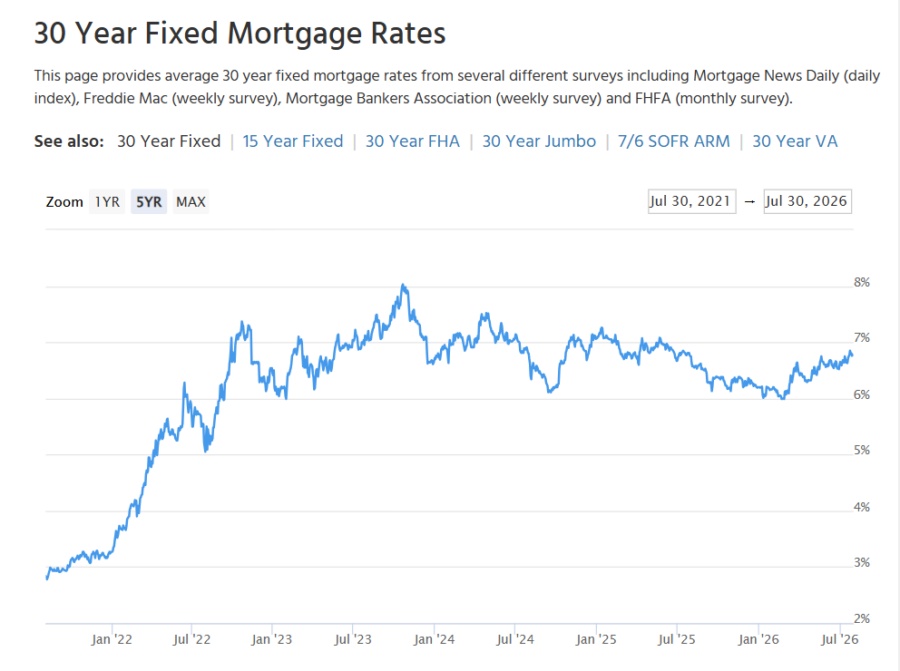
October of 2023 is also when mortgage rates peaked at 8.0%.
Prior to 2023, though, the last time the 10-Year saw yields this high was 2007 – and it took a global financial meltdown to bring them down.
The Good News:
- Mortgage to Treasury Spreads: The average mortgage rate is about 2% higher than the 10-Year yield. This remains very good news, as the spread was as high as 3% in October. Mortgage rates would be 7.7% today if those higher spreads were around today.
- Inflation remains relatively tame: June PCE inflation was released today, and “the core” (stripping out food and energy) rate remains surprisingly tame. Overall PCE still came in hot though – which is partially why rates are higher today.
- GDP is soft: The latest Gross Domestic Product report came in softer than expected, and rates tend to fall in response to slower growth (soft GDP reports).
- Crashes on the horizon? This is only good news for the mortgage industry, as stock market crashes and credit crises tend to bring down rates – often by a lot. And X remains chock full of predictions of both.
- The Iran war might end… IF it does, oil prices will plummet and rates will follow.
The Fed Held Rates Steady
The Fed did not move the Fed Funds Rate yesterday, focusing on relatively warm core inflation reports and a money supply that is not running out of control.
Although the Fed has less control over long-term rates than most people realize, it was still good news to see the Fed not raise the Fed Funds Rate.
5 Year Mortgage Rate Chart
Lastly, below is a chart of mortgage rates over the last five years – a nice reminder that mortgage rates were higher than they are now for much of the time from mid-2022 on.